From Reactive to Proactive: How Soarion Credit Union Cut Delinquency in Half
Soarion Credit Union reduced delinquency from 2.52% to 1.1% using the AKUVO Platform. See how their team shifted from reactive to proactive collections.
Ratio Decrease
3 Months
Activated
Integrations
Overview
When Melissa Esquivel-Gonzalez, Credit Solutions & Loss Mitigation Manager at Soarion Credit Union, set out to modernize how her team worked, she had a clear goal: give her collectors the tools and structure to focus on what they do best—having real conversations and finding real solutions for members. Working alongside Marcos De La Rosa, Director of Lending Technology & QA, Soarion built a collections operation designed around data, automation, and relationships. Since going live on the AKUVO platform in June 2024, Soarion has reduced its delinquency rate from 2.52% to 1.10%—including a drop from 1.94% to 1.10% in just three months. And they’re not finished yet.
Key Takeaways
- Reduced delinquency from 2.52% (2023) to 1.10% (March 2026), including a 3-month drop from 1.94% to 1.10%.
- Activated Virtual Collector, VoApps, and expanded text and email outreach in early 2026—reaching the 1–29-day segment for the first time with consistent, automated engagement.
- Reduced queue volumes by more than 50–75% across every delinquency bucket: 30–59 day queues from 350–400 accounts to 110–120; 60–89-day queues from 275–300 to 60–70; auto queues from 400–600 to 150–200 weekly.
- Automated manual workflows, including loan extensions and bankruptcy documentation, freeing collectors to focus on complex, high-value conversations.
- Built a connected ecosystem of integrations—TriVerity, Eltropy, NCCI, REPAY, BankruptcyWatch, VoApps, and State National—implemented in under a year.
“For a couple of years, we’ve been very reactive in our delinquency. Now I feel like the tide is changing—we’re becoming a little bit more proactive.”
Melissa Esquivel-Gonzalez
Goals
Soarion’s collections team had a strong foundation and a clear sense of direction. Melissa and her team knew that with the right platform, they could do more: reach members earlier, work accounts more strategically, and shift the team’s culture away from transactional collection toward genuine financial counseling.
Soarion aimed to:
• Gain clear visibility into delinquency across buckets and time frames to inform strategy.
• Establish consistent, structured workflows so every account receives timely attention.
• Automate early-stage outreach to reach members before delinquency escalated.
• Free collectors from administrative work so they could focus on complex accounts and meaningful conversations.
• Build a connected ecosystem of tools that worked together inside a single platform.
The Platform in Practice
The shift was immediate. With AKUVO, the team could see delinquency by bucket, build targeted queue strategies, and establish a consistent touch cadence for every account. Playbooks and behavioral triggers removed ambiguity from the workflow: collectors knew what to do next, and the system adapted as account status changed.
The cultural shift ran parallel to the operational one. Melissa described a deliberate move away from a transactional collections identity toward something built around solutions and relationships. Coaching evolved alongside the platform—and the team evolved with it.
“We’re becoming heroes now. We’re becoming solutions driven, versus collecting, collecting payment.”
Melissa Esquivel-Gonzalez
Queue Transformation
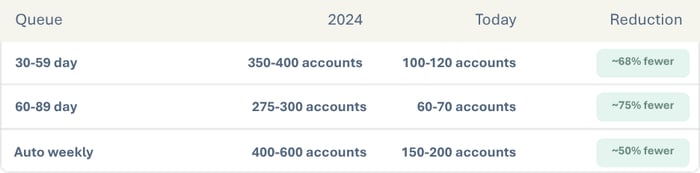
More importantly, every delinquent account now has a consistent touch cadence. The unpredictability that once defined the team’s days—cycling through accounts that hadn’t been touched in days—has given way to a steady, manageable rhythm. Collectors know where they stand. Managers know what’s been worked.
With queues under control, collectors have the time and bandwidth to tackle what matters most: loan modifications, troubled debt restructures, and the kind of extended conversations that turn a delinquency into a resolution.
Reaching Members Earlier with Virtual Collector
In early 2026, Soarion activated Virtual Collector alongside VoApps and expanded text and email outreach. The impact was immediate.
Before activation, the 1–29-day delinquency segment received inconsistent attention—touched only after higher-priority buckets were cleared, and sometimes not at all. Virtual Collector changed that. Automated outreach now begins at day one, creating a consistent presence in early delinquency that the team couldn’t previously maintain.
"Virtual Collector has really helped in stopping the overflow of an untouched audience.”
Melissa Esquivel-Gonzalez
The results surfaced quickly. Soarion saw an increase in inbound calls from members who had previously gone unreached—members who responded to early outreach and called in to get ahead of a potential problem. Extensions, deferments, and proactive restructures became possible before accounts had the chance to escalate.
For members navigating difficult moments, the difference was profound. Soarion’s team connected with members in real estate delinquency who were struggling to catch up—members who hadn’t known help was available, and who responded with genuine relief when it was offered.
Automation in Action
Operational improvements extended well beyond queue management. Soarion automated several workflows that had previously required significant manual effort.
The loan extension process—once a fully manual, PDF-driven workflow—now routes through AKUVO for submission, manager approval, and handoff to loan servicing. BankruptcyWatch pulls docket documentation directly into cases, eliminating the need to manually save, file, and retrieve documents. The platform’s behavioral logic drives next actions based on what collectors input, reducing decision fatigue and keeping accounts moving.
A Connected Ecosystem
Soarion’s platform runs on a fully connected set of integrations: TriVerity, Eltropy, NCCI, REPAY, BankruptcyWatch, VoApps, and State National.
Implementing this many integrations would have been a multi-year undertaking in most vendor environments, but with AKUVO, it took less than a year. For Marcos, the experience reset his expectations.
“AKUVO has raised the bar of what my expectations are for a vendor partnership.”
Marcos De La Rosa
The combination of well-documented integrations, knowledgeable support, and a structured implementation process meant that connectors like BankruptcyWatch went live in under a week. The platform was built to make expansion straightforward—and Soarion is already planning what comes next.
A Partnership Built on Shared Goals
For both Melissa and Marcos, the relationship with their AKUVO team has been as important as the platform itself. Weekly touchpoints, proactive guidance, and a willingness to engage with Soarion’s specific goals—not just answer questions—supported the pace Melissa and Marcos set.
"It truly feels like a partnership. They stay focused on our goals and guide us toward success using the tools we already have, rather than trying to sell us something new.”
Marcos De La Rosa
For Marcos, having an advisor who could translate platform capabilities into clear, strategic direction proved to be a meaningful differentiator. For Melissa, it meant having someone who understood the operation well enough to challenge assumptions and propose better approaches.
“If a peer credit union asked me if they should convert to AKUVO, my first question would be: does your current vendor truly act like a partner—someone invested in your success and willing to guide you along the way? Because if they’re not—that’s exactly what you’ll get with AKUVO.”
Marcos De La Rosa
Results
Since going live in June 2024, Soarion has:
• Reduced delinquency from 2.52% to 1.10%
• Driven a 3-month drop from 1.94% to 1.10% between January and March 2026.
• Established consistent outreach across the full delinquency spectrum, including the 1–29-day segment previously unreached.
• Reduced queue volume dramatically, enabling collectors to work every account on a reliable cadence.
• Built and activated 7+ platform integrations in under a year.
Conclusion
Soarion Credit Union set out to build a collections operation that matched their ambition: proactive, relationship-driven, and built to grow. Melissa Esquivel-Gonzalez and Marcos De La Rosa made deliberate, strategic decisions at every step—choosing the right platform, activating the right tools at the right time, and building a culture that put member relationships at the center of collections work.
The results speak to what’s possible when a committed team has the right infrastructure behind them. Soarion isn’t just managing delinquency more effectively—they’re redefining what their collections team can be.